The nine places a marriage or divorce changes your tax position, and which ones carry the most money
Private tax strategy for marriage, prenups, and divorce
Your tax return may reveal financial risks your relationship hasn't discussed yet.
Marriage and divorce change your tax rate, your IRS exposure, your child credits, your business income treatment, your home-sale math, and your retirement accounts. Most couples find out the hard way, at audit, at refinance, or at the divorce table. Marriage Tax Shield is a private tax engagement that surfaces these issues while you can still do something about them.
20+ Years as a Licensed CPA
MST Masters in Taxation
9 Tax Exposure Categories
Nationwide All 50 States
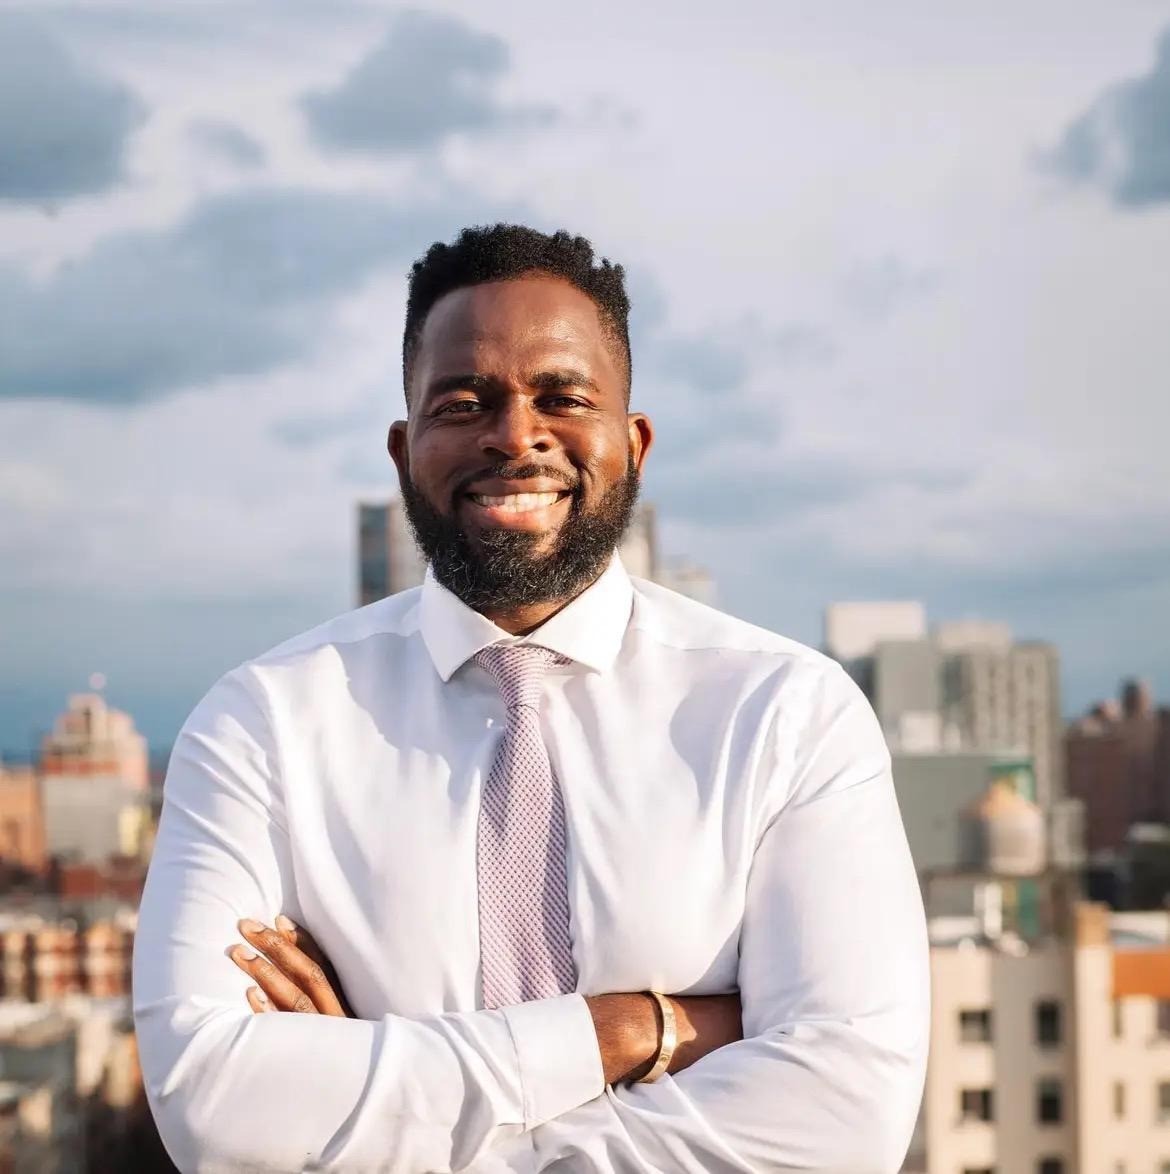 Your host: Busayo Ogunsanya, CPA, MST
Managing Partner, BigApple Accounting Tax & Advisory
As featured in
WSJ
Forbes
CRAIN'S
What the training covers
Why joint filing keeps both spouses on the hook after a separation, and the two elections that limit it
How the engagement works, what you receive in writing, and how pricing is set
Who this is for
Business owners
Schedule C, S-corp, partnership, or rental property income running through a marriage or a separation.
High-income households
Physicians, founders, executives, and K-1 partners, where a single filing election moves five figures.
Prenups and second marriages
Remarrying with children, prior obligations, or significant assets, and drafting terms that have to hold up on the return.
Separation and divorce
Considering it, negotiating it, or filing solo for the first time, and wanting the tax view alongside your attorney.
What the engagement covers
- A written position across nine tax exposure categories, prepared and reviewed by a CPA
- Filing status strategy modeled against your actual numbers
- Joint return liability exposure, the issue most couples never discuss until it is too late
- IRS debt, withholding, and audit-risk review
- Business, K-1, and rental income treatment through a marital change
- Children, dependents, and Form 8332 mechanics
- Alimony tax treatment under the post-2018 rules
- Prenup tax mechanics, documented for your attorney
- Asset-division tax modeling, including the home-sale exclusion and retirement account transfers
- A prioritized action list and the specific questions to put to your attorney
Most divorce settlements get negotiated by attorneys who do not specialize in tax. The wrong filing-status election alone can cost $8,000 to $25,000 in the year of divorce. The wrong asset-division mechanics can cost six figures over a decade.
Busayo Ogunsanya, CPA, MST
What the wrong move actually costs
$225,000
Retirement split, no QDRO
A $500,000 401(k) divided in a settlement without a qualified domestic relations order. The transfer is treated as a distribution to the account holder, taxable at ordinary rates plus a 10% early-withdrawal penalty. The same split done correctly is tax-free.
$59,500
Home sale, timed wrong
A $600,000 gain on the marital home. Sold while still married, $500,000 of that gain is excluded. Sold after the divorce is final, the exclusion drops to $250,000 for a single filer, and the extra $250,000 is taxed at capital gains rates plus the net investment income tax.
$11,400
Filing status, year of divorce
A separating parent who files married filing separately when they qualify for head of household. The result is a smaller standard deduction, narrower brackets, and the loss of several credits that married filing separately disallows outright.
These are illustrative scenarios modeled on federal tax rules, not client results. They show how the mechanics work at common income and asset levels. Your numbers depend on your own facts, your filing history, and the terms of any settlement.
Why I built this
Busayo Ogunsanya, CPA, MST
I've watched too many smart, careful people, physicians, founders, and executives, sign agreements and file returns that quietly cost them tens or hundreds of thousands of dollars in tax mistakes their attorney never flagged.
Marriage Tax Shield is the same work I do for private clients, made available to a limited number of couples before the damage is done.
Watch the private training
Engagements are limited each month and priced by complexity, starting in the five figures. The training explains the process, what you receive in writing, and how pricing is set.
- Over twenty years as a licensed CPA
- Masters in Taxation
- Founder, BigApple Accounting Tax & Advisory
- Author, What My CPA Should Have Told Me Before 40
- Featured in The Wall Street Journal, Forbes, and Crain's New York Business
Questions people ask before they book
What does it cost?
Engagements are priced by complexity, not by the hour, and they start in the five figures. A straightforward household sits at the low end. A K-1 partner with an operating business, rental property, and a settlement in negotiation sits considerably higher. You get a fixed number before any work begins, and the training walks through what drives it.
Does this replace my attorney?
No, and it is not meant to. Your attorney handles the agreement, custody, and support. This engagement produces the tax position that sits underneath those terms, written so your attorney can negotiate against real numbers instead of assumptions. Most family-law attorneys are glad to have it.
Can I do this without my spouse knowing?
Yes. The engagement is between you and this firm. Nothing is filed, nothing is reported to the IRS, and no contact is made with your spouse, their counsel, or anyone else. If a joint return is involved, the analysis works from documents you already have a legal right to.
Is this confidential?
Your information is held in confidence under professional standards governing CPAs. One thing to be clear about: CPA confidentiality is not the same as attorney-client privilege, and it does not protect communications in a contested divorce the way privilege does. If you need privileged advice, your attorney can engage this firm on your behalf, which is a common arrangement and one the training explains.
What if we have already filed?
Prior years are usually still open. Amended returns are generally available for three years from the filing date, which means a wrong filing status, a missed election, or a misallocated credit can often still be corrected. Part of the engagement is checking which open years are worth reopening and which are better left alone.
How long does it take?
It depends on the complexity of your return and whether a settlement date is driving the calendar. A straightforward W-2 household moves quickly. A K-1 partner with rental property and an S-corp takes longer. If you have a court date or a signing deadline, say so at intake and the work is sequenced around it.
Divorce is not on the table for us. Is this still relevant?
Yes, and that is the better time to do it. Filing status, joint return liability, entity structure, and how assets are titled are all easier to fix while both spouses are cooperating. Couples who come in before there is a dispute have every option available. Couples who come in during one have fewer.
Do you work with clients outside New York?
Yes. The bulk of what drives these outcomes is federal, and federal rules apply the same in every state. State-specific items and community property rules are identified and flagged for your attorney where they matter.